QuantConnect empowers quantitative researchers with code-first algorithmic trading. Stratifyre empowers active traders with no-code AI-powered strategy design, and institutional-grade tooling.
Everything you need to go from trading idea to live algorithm — without writing boilerplate.
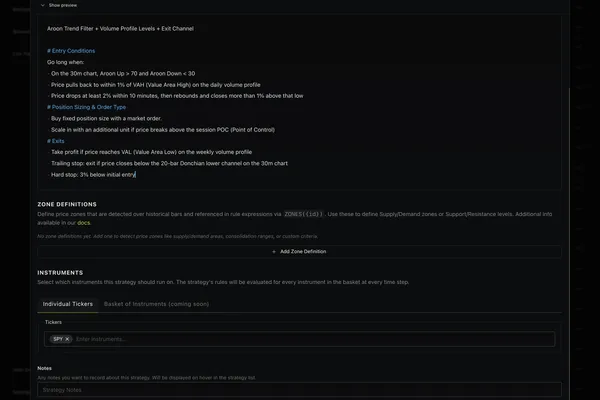
Describe your strategy in plain English. The AI generates the implementation and configures the rules.
Time-travel through your backtest. See exactly what your strategy 'saw' at any moment.
Go beyond basic win rate and profit factor.
70+ performance metrics, Monte Carlo simulation with 10,000+ iterations, tax-aware after-tax returns, and MAE/MFE trade quality analysis. Know if your strategy is robust, not just profitable in a backtest.
Learn more about Monte Carlo AnalysisSee your real after-tax performance.
The only retail platform with built-in tax modeling. Section 1256 handling for futures, wash sale detection, short/long-term capital gains brackets, and after-tax equity curves that show your actual take-home returns.
Learn more about Risk AnalysisQuantConnect requires learning the LEAN API in C# or Python. Stratifyre lets you describe your idea in plain English or build it visually — no programming language to learn.
class EMACross(QCAlgorithm):
def initialize(self):
self.set_start_date(2020, 1, 1)
self.set_cash(100000)
self.spy = self.add_equity("SPY")
self.fast = self.ema("SPY", 9)
self.slow = self.ema("SPY", 21)
def on_data(self, data):
if not self.slow.is_ready:
return
if self.fast.current.value > \
self.slow.current.value:
self.set_holdings("SPY", 1)
else:
self.liquidate("SPY")
QuantConnect and Stratifyre serve different audiences. Here's how they compare across the dimensions that matter most to active traders.
Code editor (C# / Python)
AI natural language + visual rule builder
Write code for all logic and boilerplate
Describe your idea in plain English or build visually
Steep — requires LEAN API knowledge
Gentle — visual interface with inline guidance
2-4 weeks for new users
2-4 hours including platform learning
Unlimited custom data feeds via code
Curated institutional data
Build your own execution infrastructure
Fully managed cloud execution & broker API integrations
Code, test, debug cycle
Visual changes with instant validation
Unlimited via code
120 indicators and patterns, 15 condition operators, multi-timeframe
Community-shared algorithms
AI strategy creation and natural language interface
Basic metrics (manual analysis or custom scripts)
70+ metrics, Monte Carlo, tax-aware returns, visual debugger
Building complex research algorithms
Deploying production trading strategies quickly
The best tool depends on what you're building and how you like to work. Both platforms are excellent at what they do.
See exactly how Stratifyre handles each part of the trading workflow.
AI natural language, visual rule builder, 120 indicators and patterns, 15 condition operators.
Tick-level data, 4 fill modes, visual debugger, corporate action handling.
70+ metrics, tax-aware returns, MAE/MFE analysis, drawdown duration tracking.
10,000+ simulations, confidence bands, parameter sensitivity analysis.
Monitor 1,000+ instruments in real-time with multi-channel alerts.
Direct broker integration with Alpaca, IBKR, TradeStation, and Tradier.
There's no direct import path since the two platforms use fundamentally different paradigms (code-first vs. no-code). However, most strategy logic can be rebuilt using Stratifyre's AI strategy builderin 30-60 minutes by describing what your strategy does in plain English. For indicator-based strategies, the transition is straightforward. Highly custom logic that relies on raw Python/C# code may not have a direct equivalent in a no-code platform.
The visual builder covers a wide range of common trading strategies, including multi-timeframe logic, complex indicator combinations (120 indicators and patterns, 15 condition operators), and advanced order types. You trade some raw flexibility for dramatically faster iteration speed and capabilities that are difficult to build in code: avisual debugger,Monte Carlo validation, and tax-aware returns.
Both platforms offer professional-grade backtesting. QuantConnect provides an extensive data library with tick-level granularity and deep historical coverage across many asset classes. Stratifyre offers institutional-grade data via Databento (nanosecond precision, 70+ corporate action types), a visual debugger (Strategy Replay) that lets you time-travel through your backtest, 4 fill simulation modes, and70+ performance metricsincluding tax-aware returns.
Yes. No-code does not mean toy. Stratifyre provides direct broker integration (Alpaca, IBKR, TradeStation, Tradier), institutional-grade data via Databento, and professional analytics includingMonte Carlo simulationand 70+ performance metrics. Professional traders use visual tools because they're more efficient, not because they can't code.
Stratifyre currently supports trading and scanning for US Equities, Futures, and Crypto. While QuantConnect supports a broader set of international markets and niche derivatives, we focus on providing the highest quality data, performance, and execution for our supported asset classes.
QuantConnect offers a free tier with paid tiers ranging from $8 to $400+ per month, scaling with compute resources and data access. Stratifyre usespay-as-you-go pricingwith $50 in free credits to start — no subscription required. You only pay for the compute and data you actually use. For context, a typical active trader running daily scanners and 10 backtests a week might spend just ~$15/month.
Absolutely. A reasonable workflow is to use QuantConnect for complex quantitative research where you need full programmatic control, then use Stratifyre for faster iteration on indicator-based strategies withvisual debugging,Monte Carlo validation, and direct broker execution. The platforms serve different stages of the trading workflow.
Describe your strategy in plain English. Backtest with institutional-grade data. No code, no setup, no boilerplate.